Medicare Open Enrollment lets you reshape healthcare coverage and lower out-of-pocket medical bills for the upcoming year. Reviewing options protects your household budget against unexpected plan changes taking effect in 2027.
Between October 15 and December 7, you can switch Medicare Advantage plans, adjust prescription drug coverage, or return to Original Medicare. Taking action ensures your insurance matches your evolving medical needs.
This guide explains essential deadlines, new cost caps, and benefit programs so you can make informed choices with confidence.
Key Dates and Deadlines for 2027 Medicare Enrollment
Marking your calendar ensures you secure the right plan before federal deadlines expire. Missing these windows limits your ability to adjust medical or drug coverage for an entire calendar year.
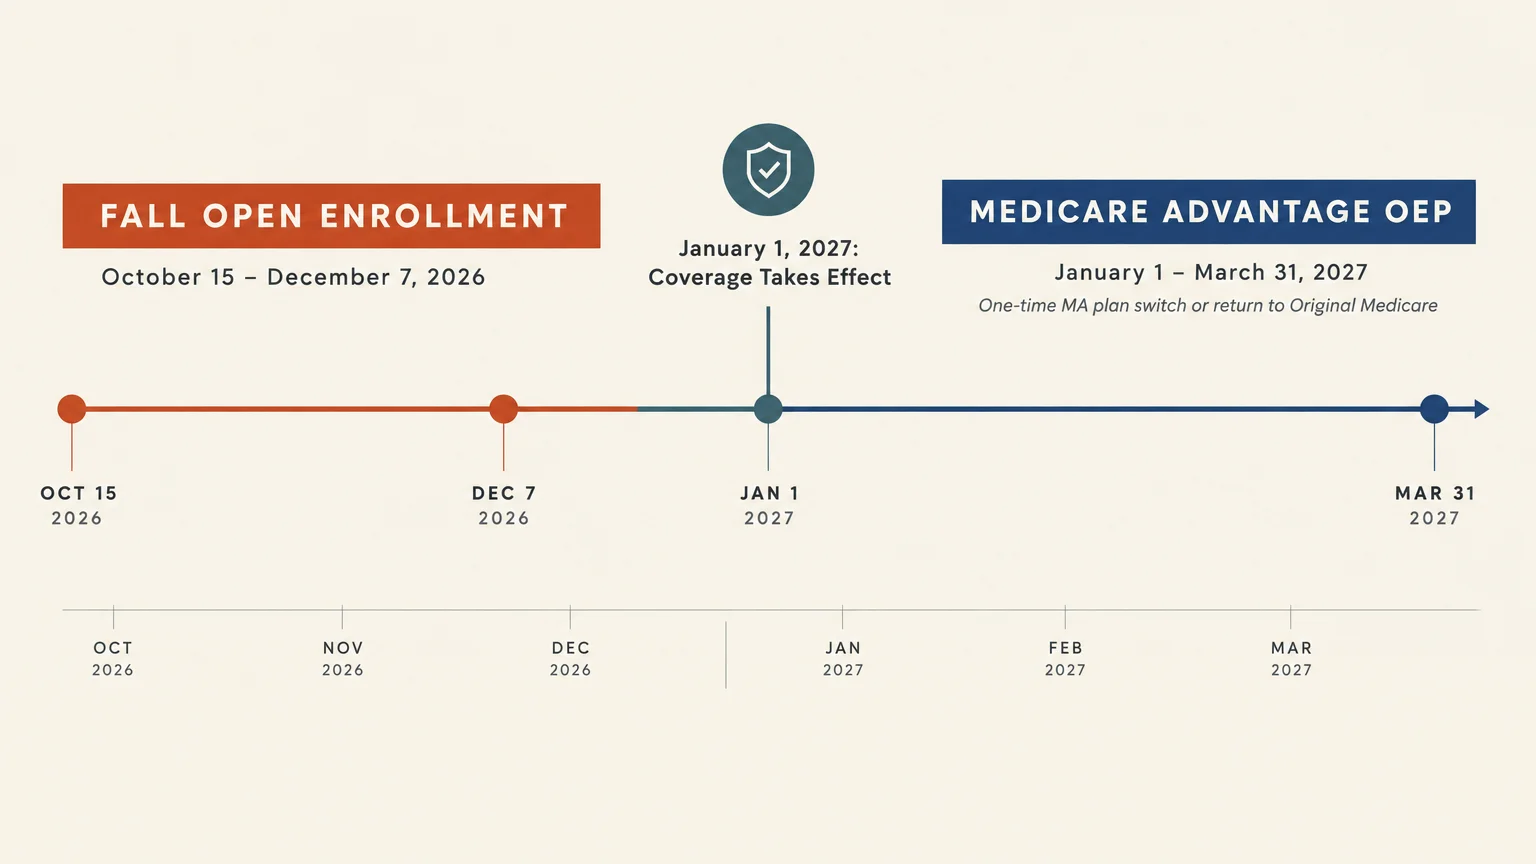
The Fall Open Enrollment Window: October 15 to December 7, 2026
The primary Medicare Open Enrollment Period—also called the Annual Enrollment Period (AEP)—runs from October 15 through December 7, 2026. This seven-week window is your main opportunity to join, switch, or drop plans.
Plan changes submitted by midnight on December 7 apply to your 2027 healthcare benefits. Reviewing plan materials in early October provides ample time to compare formularies and provider networks.
When Your 2027 Coverage Takes Effect: January 1, 2027
All plan selections submitted during the fall window take effect on January 1, 2027. Your previous coverage terminates automatically on New Year’s Eve, preventing any protection gap.
Insurers mail new membership cards and policy documents before January. If materials do not arrive promptly, contact your plan provider to confirm your enrollment details.
The Medicare Advantage Open Enrollment Window: January 1 to March 31, 2027
If you have a Medicare Advantage (Part C) plan on January 1, 2027, you get another adjustment window. The Medicare Advantage Open Enrollment Period (MA OEP) spans from January 1 through March 31, 2027.
During these three months, you can make a one-time switch to another Medicare Advantage plan. Alternatively, you can drop Medicare Advantage, return to Original Medicare, and enroll in a standalone Part D plan.
This period does not allow switching between standalone Part D plans if you remain on Original Medicare. It serves exclusively as a safety net for Medicare Advantage enrollees.