Income and Asset Rules You Need to Know
How Countable Monthly Income Works
Federal poverty guidelines establish the baseline income criteria for every Medicare Savings Program. Program calculations incorporate an automatic $20 general monthly income disregard.
For 2026, individual monthly income caps are $1,350 for QMB, $1,616 for SLMB, and $1,816 for QI. Married couples face limits of $1,824 for QMB, $2,184 for SLMB, and $2,455 for QI.
Countable income includes Social Security checks, pension distributions, wages, and interest payments. The state deducts the standard $20 disregard from your unearned income before evaluating your eligibility.
Alaska and Hawaii maintain higher income thresholds to account for elevated regional living costs. You can explore regional criteria through medicareinteractive.org for in-depth guidance.
Federal Asset Limits and Exempt Resources
Federal regulations also evaluate your financial assets before granting program approval. In 2026, countable resource limits are $9,950 for individuals and $14,910 for married couples.
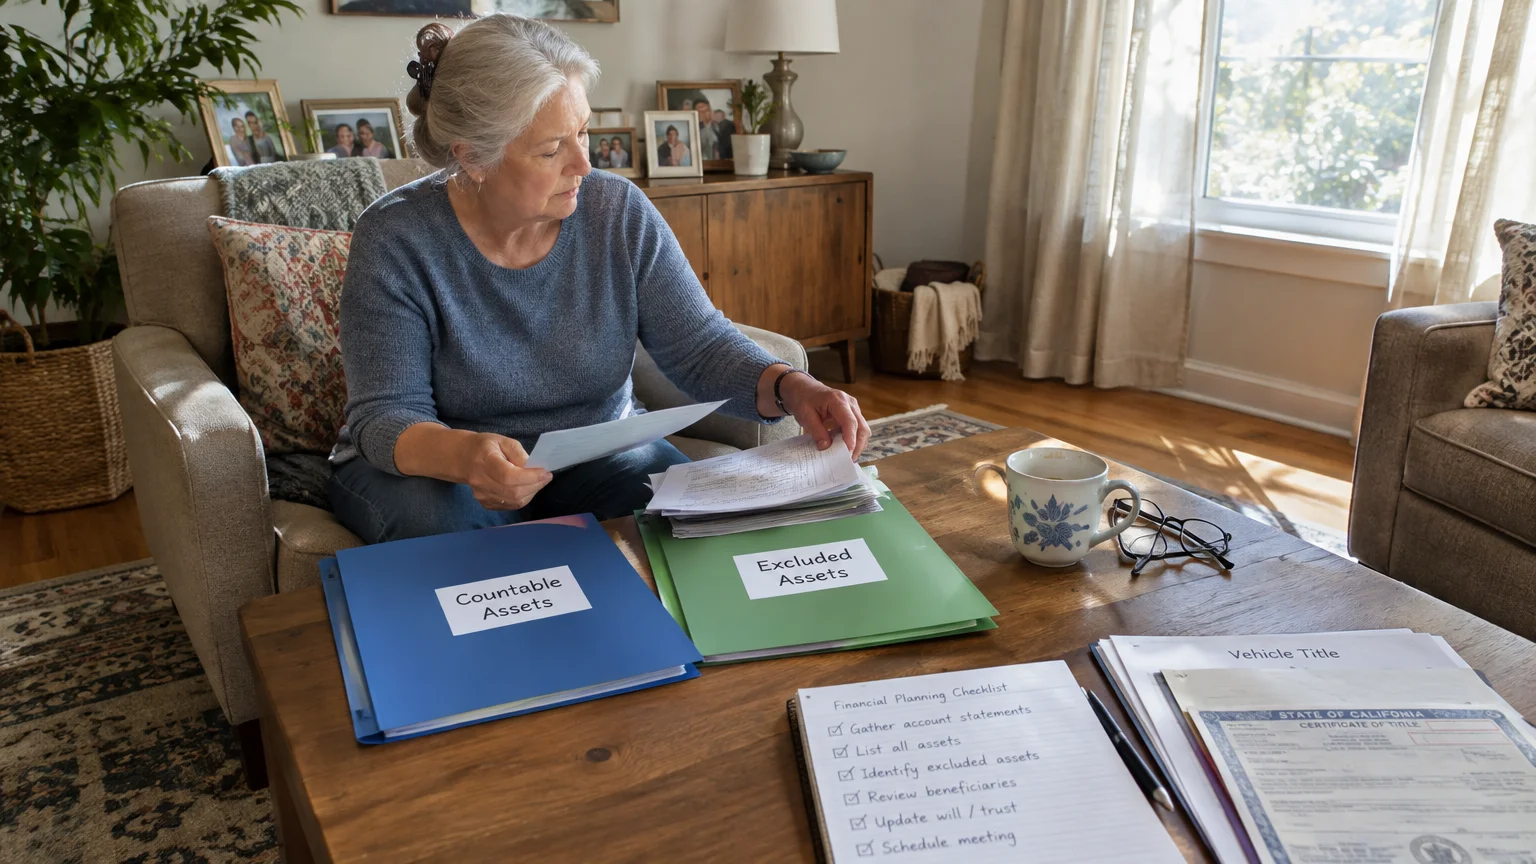
Countable assets include cash, checking accounts, savings accounts, certificates of deposit, stocks, and bonds. The state tallies these accounts when determining your financial eligibility.
Fortunately, federal rules exempt several major possessions from this calculation entirely. Your primary residence, the land it occupies, and one personal vehicle do not count.
The government also excludes personal effects, everyday household goods, and up to $1,500 per person set aside in designated burial funds.
State-Level Asset Test Variations
Several states have recognized that federal asset limits place an unnecessary hurdle in front of needy seniors. Consequently, these states have modified or removed resource tests completely.
California and New York, for example, have eliminated asset limits entirely for Medicare Savings Programs. In those states, your eligibility depends solely on your monthly income.
Other states have substantially increased asset allowances above the federal standard. Even if your personal savings exceed $9,950, you should verify your local state rules.