Medicare Part D Penalty: Prescription Coverage Gaps
Medicare Part D delivers outpatient prescription drug coverage through private insurance plans. Even if you do not currently take medications, enrolling on time remains essential.
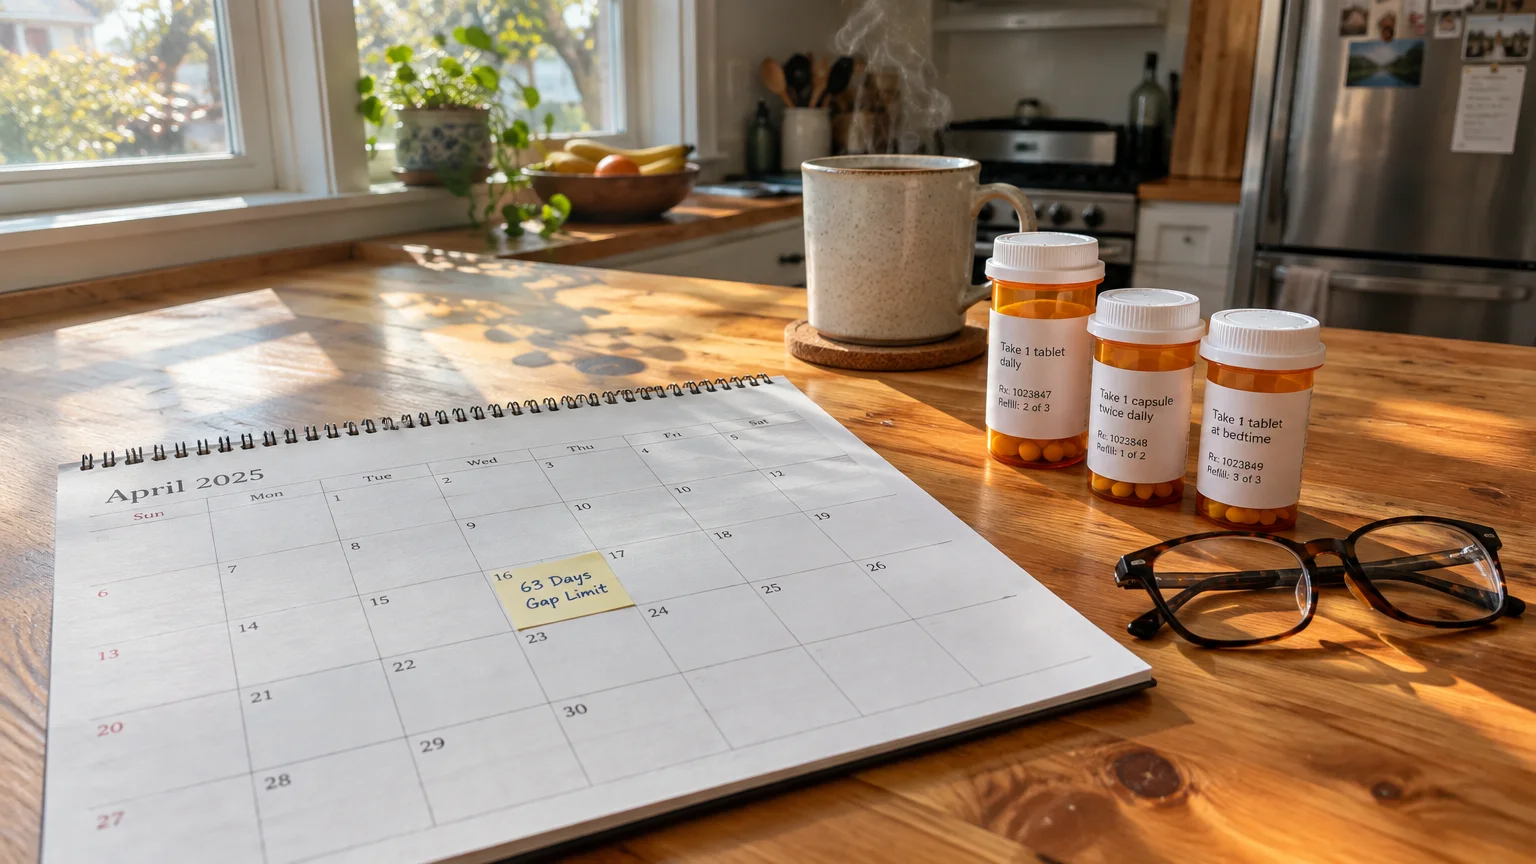
Medicare triggers the Part D penalty whenever you go 63 or more consecutive days without creditable prescription drug coverage after your Initial Enrollment Period ends.
What Counts as Creditable Prescription Coverage
Creditable coverage refers to health insurance expected to pay at least as much as standard Medicare drug plans. Common sources include active employer group coverage, union plans, and veterans benefits.
Every September, your plan sponsor must send you a written Notice of Creditable Coverage. Keep this document in your permanent files as proof of continuous insurance.
How the Part D Penalty Is Calculated
Medicare calculates the Part D penalty by multiplying 1% of the national base beneficiary premium by your total number of full uncovered months.
The government rounds this calculation to the nearest ten cents. You must pay this surcharge in addition to your plan’s regular monthly premium.
For 2026, the national base beneficiary premium is $38.99. For 2027, CMS has finalized the national base beneficiary premium at $41.33.
The 2027 base rate reflects the 6% annual statutory cap mandated by the Inflation Reduction Act through 2029. Because the base premium adjusts annually, your penalty recalculates every January.
This penalty lasts permanently; you must pay it even if you select a Medicare Advantage plan or Part D plan with a $0 monthly premium.
Beneficiaries who qualify for the federal Extra Help program—also known as the Low-Income Subsidy (LIS)—do not have to pay any Part D late enrollment penalty.
Worked Example: The Part D Calculation in Action
Consider Maria, who went without creditable prescription drug coverage for 14 full months after her Initial Enrollment Period closed.
In 2026, Medicare multiplies 14% by the base premium of $38.99, yielding $5.46. Rounded to the nearest dime, Maria pays an extra $5.50 per month.
In 2027, the base rate climbs to $41.33. Her penalty recalculates as 14% of $41.33, which equals $5.79 and rounds to $5.80 every month.
Maria must pay this fee indefinitely alongside her plan’s regular premium. Enrolling in a low-cost drug plan at 65 would have completely prevented these ongoing fees.