Real-World Example: Calculating Your 2027 Prescription Savings
Understanding how the deductible, coinsurance, and annual cap function together helps you budget accurately. Let us look at a practical scenario.
Case Study: Margaret’s Monthly Expenses
Margaret is 70 and enrolled in Original Medicare with a stand-alone Part D plan. She takes a brand-name medication that costs $800 each month at retail.
Margaret’s plan features the standard 2027 benefit design with a $700 deductible and 25% coinsurance. Here is how her spending unfolds across the year.
Month-by-Month Spending Progression
In January, Margaret pays her $700 deductible plus 25% coinsurance on the remaining $100. Her total pharmacy bill in January is $725.
Having fulfilled her deductible, Margaret pays 25% coinsurance from February through August. Her out-of-pocket cost is $200 each month ($800 retail cost multiplied by 25%).
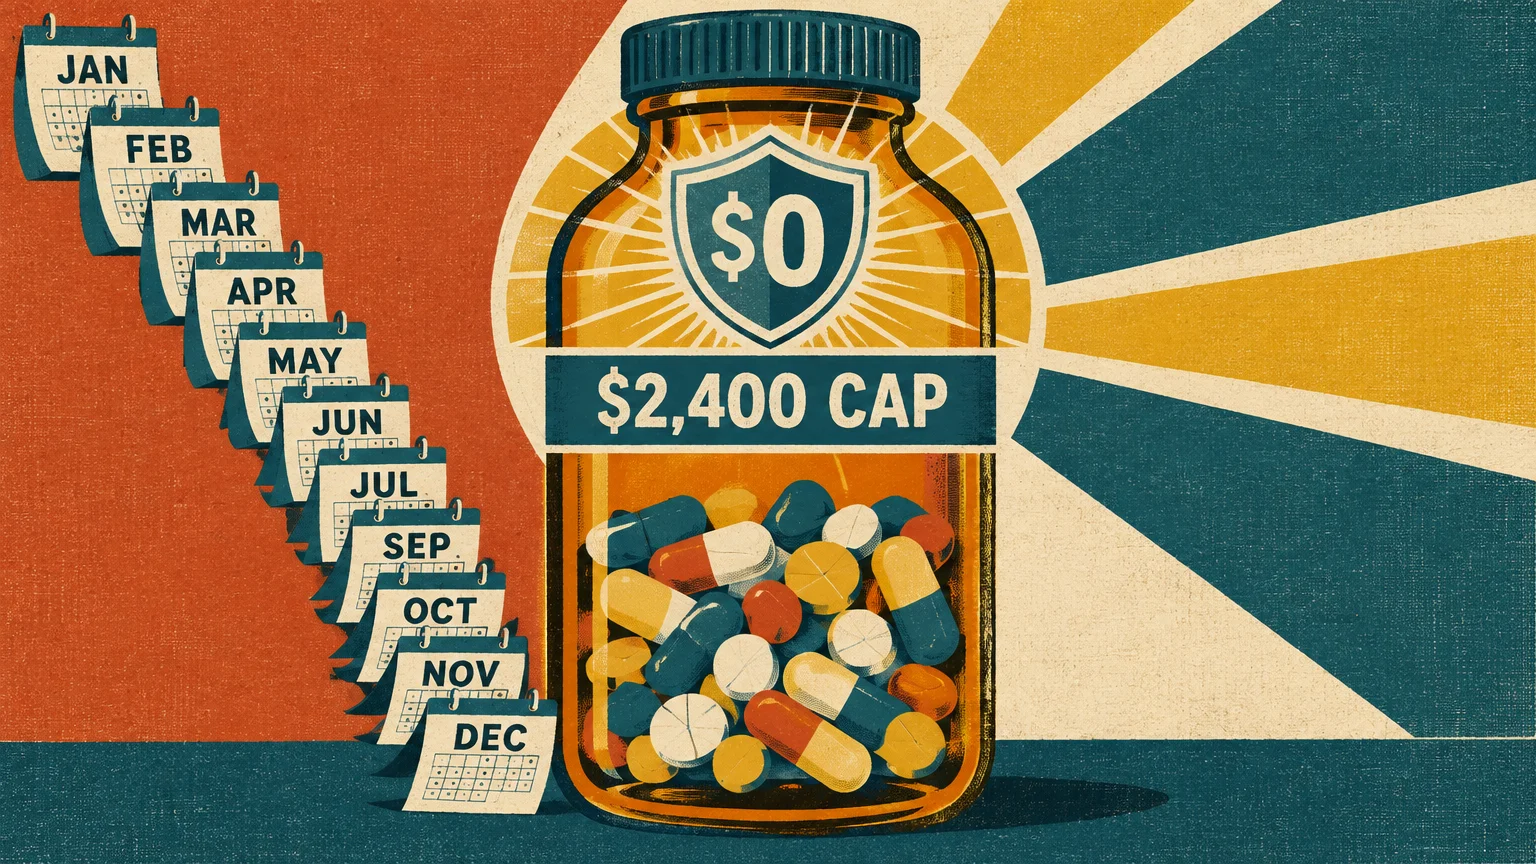
By the end of August, Margaret has paid $2,125 out of pocket ($725 in January plus $1,400 across seven months). She is now $275 away from the $2,400 cap.
In September, Margaret pays $200, bringing her cumulative total to $2,325. In October, she pays only $75 to reach the $2,400 ceiling.
For November and December, Margaret enters the catastrophic coverage phase and pays $0. Her total out-of-pocket spending for the full calendar year stops at exactly $2,400.
Annual Savings Under the 2027 Rules
Without the $2,400 cap, Margaret would have spent thousands of dollars more over twelve months. The out-of-pocket limit caps her exposure and brings predictability to her household budget.