How to Evaluate Costs and Choose the Right Policy
How Insurers Price Medigap Premiums
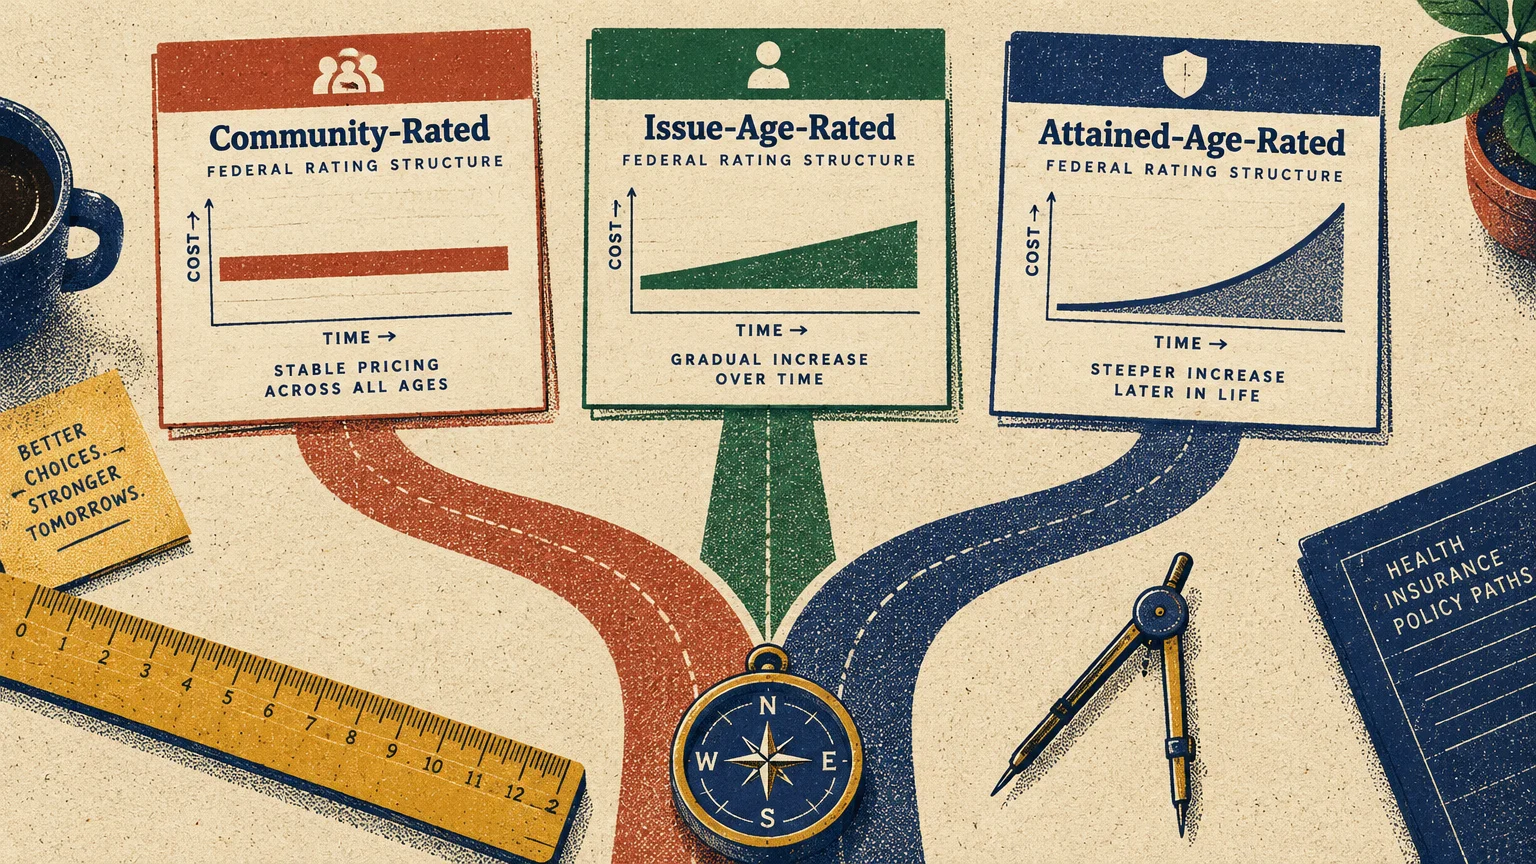
Insurance companies use three distinct rating methods to calculate monthly Medigap premiums. Understanding these pricing models helps you project how your rate will change over time.
Community-rated policies charge everyone enrolled in the same geographic area the same monthly premium, regardless of age. Premiums may increase over time due to inflation, but never because you get older.
Issue-age-rated policies base your premium on your age when you purchase the plan. Younger buyers pay lower starting rates, and premiums do not increase simply because you age.
Attained-age-rated policies calculate premiums based on your current age. These plans start with lower initial premiums but increase predictably as you grow older, often becoming expensive in your late seventies and eighties.
Finding Free and Unbiased Guidance
Before purchasing coverage, compare identical lettered plans across multiple private carriers. Premium rates can vary by hundreds of dollars annually for identical medical benefits.
Advisors can also check if you qualify for state-sponsored Medicare Savings Programs that help lower-income enrollees cover Part B premiums and other routine expenses.
Contact your local State Health Insurance Assistance Program (SHIP) for free, confidential, and unbiased counseling. SHIP counselors do not sell insurance policies and provide objective advice tailored to your financial circumstances.
You can also call 1-800-MEDICARE (1-800-633-4227) at any time to verify policy details and confirm insurer licensing in your state.