Crucial Enrollment Rules, Deadlines, and Pre-Existing Conditions
The Medigap Open Enrollment Window
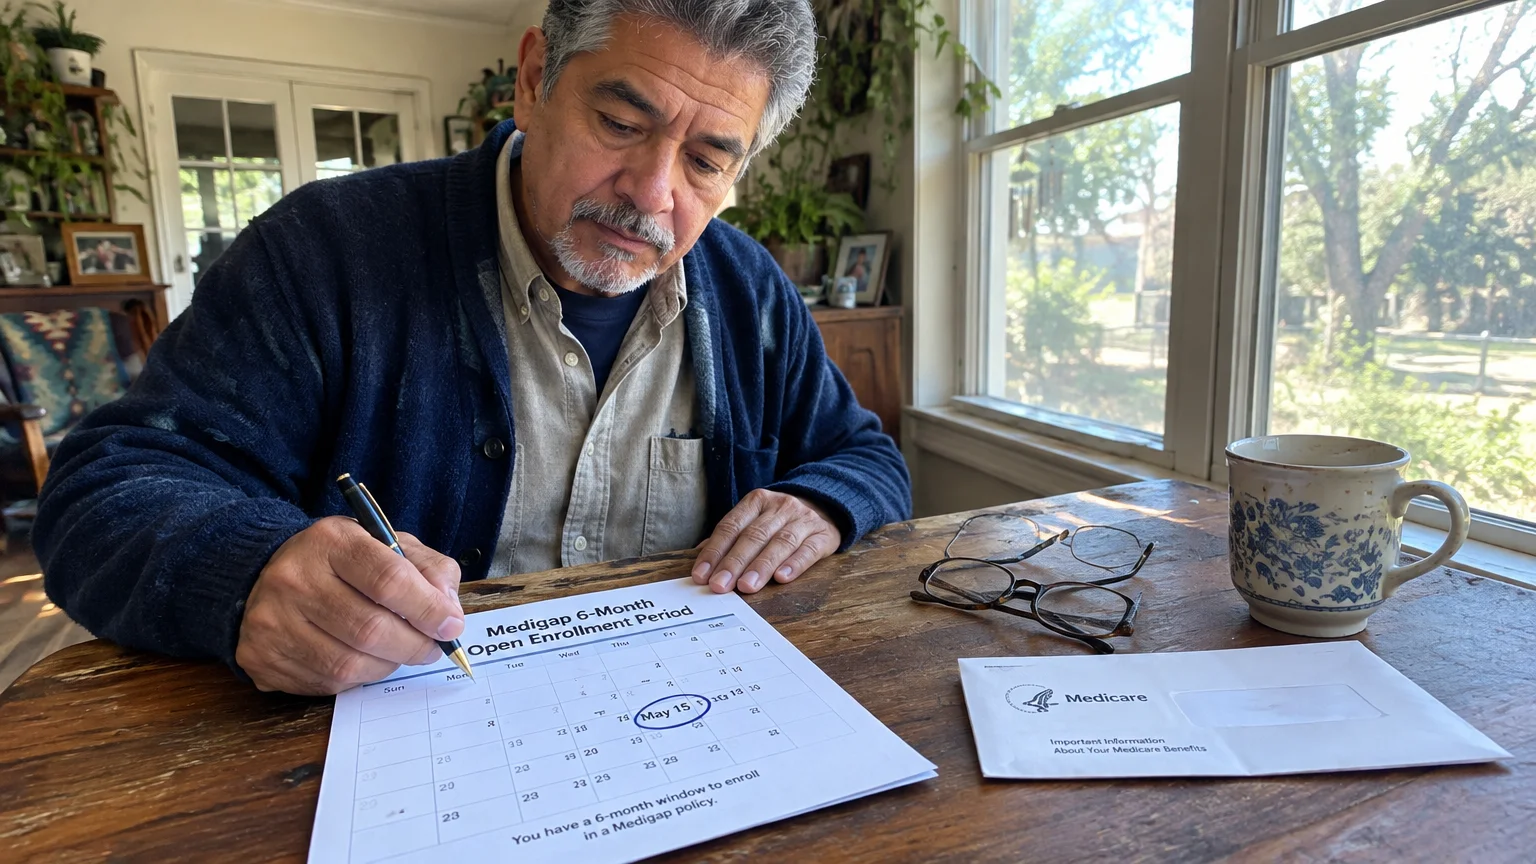
Your one-time Medigap Open Enrollment Period begins the first month you are both age 65 or older and enrolled in Medicare Part B. This critical window lasts exactly six consecutive months.
Enrolling during this timeframe also prevents you from accumulating lifelong Medicare late enrollment penalties if you have delayed your Part B coverage without creditable insurance.
Federal law gives you guaranteed issue rights throughout this six-month timeframe. Insurance carriers cannot reject your application, delay your coverage, or charge higher monthly rates because of pre-existing health conditions.
If you delay enrolling past this window without qualifying for a special enrollment period, insurers can require medical underwriting. Insurers may charge substantially higher premiums or deny your application entirely based on your medical history.
The 2020 Eligibility Cutoff for Plans C and F
Federal legislation changed Medigap availability through the Medicare Access and CHIP Reauthorization Act (MACRA). Starting January 1, 2020, insurers can no longer sell Plans C and F to individuals newly eligible for Medicare.
Lawmakers eliminated first-dollar coverage plans that pay the Part B deductible to discourage unnecessary doctor visits. Consequently, Plan G serves as the primary comprehensive alternative for people enrolling today.
If you became eligible for Medicare before January 1, 2020, federal rules still allow you to purchase or keep Plan C or Plan F. However, these plans often carry higher premiums than Plan G.