Comparing Costs, Premiums, and Out-of-Pocket Limits
Original Medicare Costs and Predictability
Understanding out-of-pocket exposure helps avoid unexpected medical bills. Original Medicare relies on standardized deductibles and fixed coinsurance rates.
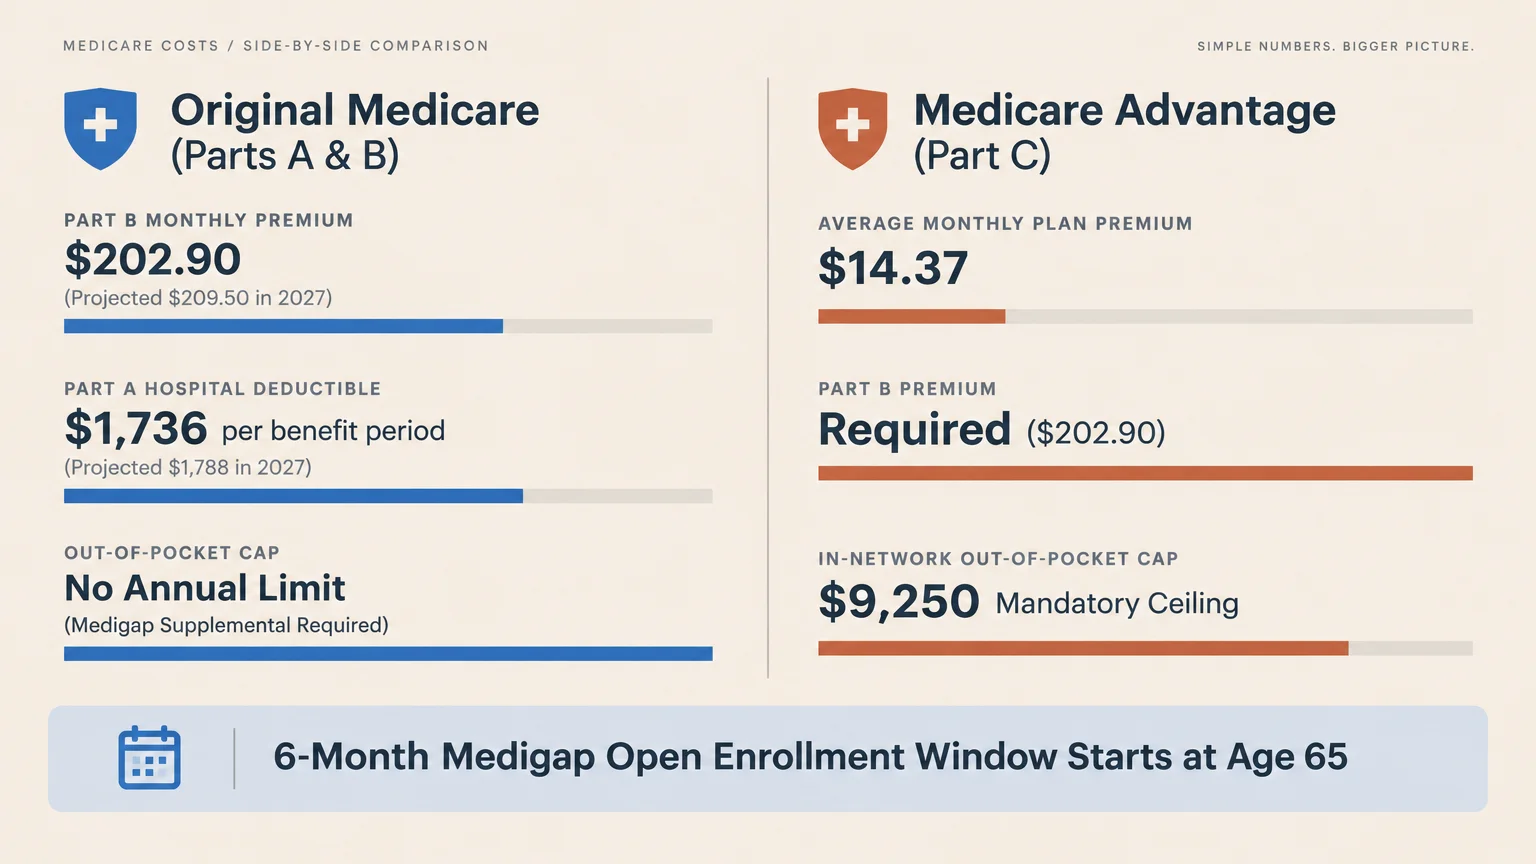
For Part A hospital stays, you pay a $1,736 deductible per benefit period in 2026. Federal projections place this Part A deductible at $1,788 for 2027.
A benefit period begins when entering a hospital and ends after 60 consecutive days outside inpatient care. Re-entering after 60 days triggers another deductible.
Approximately 99% of beneficiaries pay a $0 monthly premium for Part A due to qualifying payroll taxes. Part B medical insurance requires an ongoing monthly premium.
The standard Part B premium is $202.90 monthly in 2026. The Medicare Trustees Report projects $209.50 monthly for 2027, awaiting official late-fall confirmation from the Centers for Medicare & Medicaid Services (CMS).
After paying a Part B deductible of $283 in 2026 (projected to reach $292 in 2027), you pay 20% coinsurance. Original Medicare has no annual ceiling on this coinsurance.
Many beneficiaries purchase Medicare Supplement Insurance (Medigap) to cover this financial risk. Medigap policies pay deductibles and coinsurance in exchange for an additional monthly premium.
Medicare Advantage Premiums and Spending Caps
Medicare Advantage plans structure cost-sharing differently, often using flat copayments instead of percentage coinsurance. Enrollees must still pay the standard Part B monthly premium.
Many private plans market zero-dollar price points. About 70% of Medicare Advantage plans offering drug coverage charge a $0 additional monthly premium.
Across all enrollees, the enrollment-weighted average monthly premium is $14.37 in 2026. CMS projects this average to drop to $12.00 in 2027.
Federal law protects Medicare Advantage members by establishing a mandatory Maximum Out-of-Pocket (MOOP) spending limit on Part A and Part B services. Once reaching this cap, the plan covers 100% of covered services.
In 2026, the federal in-network MOOP ceiling is $9,250, rising to $9,850 in 2027. For Preferred Provider Organization (PPO) plans combining network care, the cap is $13,900 in 2026 and $14,800 in 2027.
Individual insurers frequently set lower limits to remain competitive. The median in-network spending limit across all plans is $6,500 in 2026, projected to rise to $7,100 in 2027.